

The Indian Rupee stayed near record lows during the week despite repeated RBI interventions, as rising Brent crude prices, geopolitical uncertainty, and foreign fund outflows continued to pressure the currency. Markets now await crude movements and upcoming capital inflows for direction.
Read More
The Indian Rupee stayed near record lows during the week despite repeated RBI interventions, as rising Brent crude prices, geopolitical uncertainty, and foreign fund outflows continued to pressure the currency. Markets now await crude movements and upcoming capital inflows for direction.
The rupee's recovery has unravelled as escalating tensions in the Middle East, higher oil prices, and a widening trade deficit push the currency back toward record lows. The analysis explores the RBI's intervention strategy, inflation risks, and why India's dependence on imported crude remains its biggest structural vulnerability.
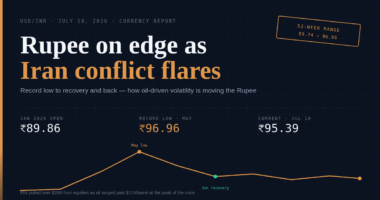
The Indian Rupee has swung between record lows and sharp recoveries in 2026 as geopolitical tensions, crude oil prices, RBI intervention, and foreign investor flows continue to shape the currency's outlook.
The Indian rupee has weakened amid persistent US dollar strength, corporate dollar demand, and arbitrage activity between onshore and offshore markets. While lower crude oil prices and RBI intervention have limited the decline, investors remain focused on upcoming Federal Reserve decisions and US inflation data to gauge the rupee's next move.
The Indian rupee climbed to 94.49 against the US dollar, its strongest level in seven weeks, after a US-Iran peace agreement triggered a sharp decline in global oil prices. With India heavily dependent on imported crude, lower energy costs are easing pressure on the current account deficit, supporting the currency, and improving the outlook for inflation and monetary policy. Investors are now watching whether the peace deal is formally signed and whether oil prices continue to trend lower.
The Indian rupee strengthened to 95.20 against the US dollar on Monday as optimism over a possible US-Iran peace agreement, falling crude oil prices, and progress in India-US trade negotiations boosted market sentiment. Investors are now closely watching the RBI’s $5 billion USD/INR swap auction scheduled this week.
Indian stock markets extended their rally for a second consecutive session on November 17, 2026. The Sensex gained 427.40 points to close at 82,532.19, while the Nifty 50 advanced 96.30 points to 25,387.40. Banking and Realty stocks led the gains, supported by falling crude oil prices and continued FII buying, while IT stocks remained under pressure.
Indian benchmark indices ended marginally higher on November 12, 2026, as buying in banking, financial services and realty stocks offset weakness in Auto, FMCG and IT. The Nifty 50 gained 44.30 points to close at 25,299.35, while the Sensex advanced 31.61 points to 81,911.01. Bank Nifty surged 726.10 points for a third consecutive session of gains. Strong October insurance premium data, continued FII inflows and easing crude oil prices supported sentiment.
Foreign Portfolio Investors (FPIs) pumped ₹53,739 crore into Indian equities across six trading sessions between November 2 and 9, 2026, reversing the outflows recorded in September and October. Buying was concentrated in heavyweight sectors such as financial services, IT, automobiles and telecom. Improved sentiment following US midterm election results, expectations of lower US bond yields, Brent crude falling below $90 a barrel and a stronger rupee supported the inflows. Meanwhile, concerns over returns from AI infrastructure and data-centre investments prompted investors to reduce crowded AI-related positions. Corporate earnings also provided support, with 27 of the 47 Nifty 50 companies reporting results by November 10 beating analysts' estimates.
Indian markets extended their post-Diwali rally on November 11, with the Sensex rising over 1,260 points and the Nifty gaining 1.35%. Easing crude prices, strong FPI buying and supportive technical indicators boosted sentiment.
Indian stock markets extended their rally for a second consecutive session on November 17, 2026. The Sensex gained 427.40 points to close at 82,532.19, while the Nifty 50 advanced 96.30 points to 25,387.40. Banking and Realty stocks led the gains, supported by falling crude oil prices and continued FII buying, while IT stocks remained under pressure.
Indian benchmark indices ended marginally higher on November 12, 2026, as buying in banking, financial services and realty stocks offset weakness in Auto, FMCG and IT. The Nifty 50 gained 44.30 points to close at 25,299.35, while the Sensex advanced 31.61 points to 81,911.01. Bank Nifty surged 726.10 points for a third consecutive session of gains. Strong October insurance premium data, continued FII inflows and easing crude oil prices supported sentiment.
Foreign Portfolio Investors (FPIs) pumped ₹53,739 crore into Indian equities across six trading sessions between November 2 and 9, 2026, reversing the outflows recorded in September and October. Buying was concentrated in heavyweight sectors such as financial services, IT, automobiles and telecom. Improved sentiment following US midterm election results, expectations of lower US bond yields, Brent crude falling below $90 a barrel and a stronger rupee supported the inflows. Meanwhile, concerns over returns from AI infrastructure and data-centre investments prompted investors to reduce crowded AI-related positions. Corporate earnings also provided support, with 27 of the 47 Nifty 50 companies reporting results by November 10 beating analysts' estimates.
Indian markets extended their post-Diwali rally on November 11, with the Sensex rising over 1,260 points and the Nifty gaining 1.35%. Easing crude prices, strong FPI buying and supportive technical indicators boosted sentiment.


 IIFL Customer Care Number
(Gold/NCD/NBFC/Insurance/NPS)
1860-267-3000 / 7039-050-000
 IIFL Capital Services Support WhatsApp Number
+91 9892691696
Download The App Now


Follow us on


2026, IIFL Capital Services Ltd. All Rights Reserved

IIFL Capital Services Limited - Stock Broker SEBI Regn. No: INZ000164132 (Member ID - NSE: 10975 BSE: 179 MCX: 55995 NCDEX: 01249), DP SEBI Reg. No. IN-DP-185-2016, Merchant Banker SEBI Regn. No. INM000010940, RA SEBI Regn. No: INH000000248, BSE Enlistment Number (RA): 5016, AMFI-Registered Mutual Fund Distributor & SIF Distributor
ARN NO : 47791 (Date of initial registration – 17/02/2007; Current validity of ARN – 08/02/2027), PFRDA Reg. No. PoP 20092018, IRDAI Corporate Agent (Composite) : CA1099

This Certificate Demonstrates That IIFL As An Organization Has Defined And Put In Place Best-Practice Information Security Processes.


