

RBI raises the repo rate by 25 bps to 5.50%, its first hike since February 2023, while shifting to calibrated tightening. FY27 GDP growth forecast rises to 7.1%.
Read More


RBI raises the repo rate by 25 bps to 5.50%, its first hike since February 2023, while shifting to calibrated tightening. FY27 GDP growth forecast rises to 7.1%.
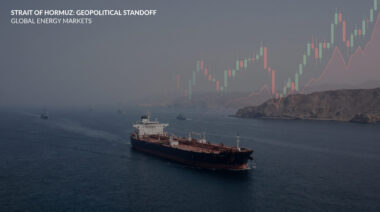
The renewed US-Iran conflict and uncertainty around the Strait of Hormuz are putting oil prices and global markets under pressure. Here’s how prolonged disruption could affect crude, inflation and stock markets in India, the US and Europe.
Indian stock markets extended their rally for a second consecutive session on November 17, 2026. The Sensex gained 427.40 points to close at 82,532.19, while the Nifty 50 advanced 96.30 points to 25,387.40. Banking and Realty stocks led the gains, supported by falling crude oil prices and continued FII buying, while IT stocks remained under pressure.
Indian benchmark indices ended marginally higher on November 12, 2026, as buying in banking, financial services and realty stocks offset weakness in Auto, FMCG and IT. The Nifty 50 gained 44.30 points to close at 25,299.35, while the Sensex advanced 31.61 points to 81,911.01. Bank Nifty surged 726.10 points for a third consecutive session of gains. Strong October insurance premium data, continued FII inflows and easing crude oil prices supported sentiment.
Foreign Portfolio Investors (FPIs) pumped ₹53,739 crore into Indian equities across six trading sessions between November 2 and 9, 2026, reversing the outflows recorded in September and October. Buying was concentrated in heavyweight sectors such as financial services, IT, automobiles and telecom. Improved sentiment following US midterm election results, expectations of lower US bond yields, Brent crude falling below $90 a barrel and a stronger rupee supported the inflows. Meanwhile, concerns over returns from AI infrastructure and data-centre investments prompted investors to reduce crowded AI-related positions. Corporate earnings also provided support, with 27 of the 47 Nifty 50 companies reporting results by November 10 beating analysts' estimates.
Indian markets extended their post-Diwali rally on November 11, with the Sensex rising over 1,260 points and the Nifty gaining 1.35%. Easing crude prices, strong FPI buying and supportive technical indicators boosted sentiment.
Indian stock markets extended their rally for a second consecutive session on November 17, 2026. The Sensex gained 427.40 points to close at 82,532.19, while the Nifty 50 advanced 96.30 points to 25,387.40. Banking and Realty stocks led the gains, supported by falling crude oil prices and continued FII buying, while IT stocks remained under pressure.
Indian benchmark indices ended marginally higher on November 12, 2026, as buying in banking, financial services and realty stocks offset weakness in Auto, FMCG and IT. The Nifty 50 gained 44.30 points to close at 25,299.35, while the Sensex advanced 31.61 points to 81,911.01. Bank Nifty surged 726.10 points for a third consecutive session of gains. Strong October insurance premium data, continued FII inflows and easing crude oil prices supported sentiment.
Foreign Portfolio Investors (FPIs) pumped ₹53,739 crore into Indian equities across six trading sessions between November 2 and 9, 2026, reversing the outflows recorded in September and October. Buying was concentrated in heavyweight sectors such as financial services, IT, automobiles and telecom. Improved sentiment following US midterm election results, expectations of lower US bond yields, Brent crude falling below $90 a barrel and a stronger rupee supported the inflows. Meanwhile, concerns over returns from AI infrastructure and data-centre investments prompted investors to reduce crowded AI-related positions. Corporate earnings also provided support, with 27 of the 47 Nifty 50 companies reporting results by November 10 beating analysts' estimates.
Indian markets extended their post-Diwali rally on November 11, with the Sensex rising over 1,260 points and the Nifty gaining 1.35%. Easing crude prices, strong FPI buying and supportive technical indicators boosted sentiment.


 IIFL Customer Care Number
(Gold/NCD/NBFC/Insurance/NPS)
1860-267-3000 / 7039-050-000
 IIFL Capital Services Support WhatsApp Number
+91 9892691696
Download The App Now


Follow us on


2026, IIFL Capital Services Ltd. All Rights Reserved

IIFL Capital Services Limited - Stock Broker SEBI Regn. No: INZ000164132 (Member ID - NSE: 10975 BSE: 179 MCX: 55995 NCDEX: 01249), DP SEBI Reg. No. IN-DP-185-2016, Merchant Banker SEBI Regn. No. INM000010940, RA SEBI Regn. No: INH000000248, BSE Enlistment Number (RA): 5016, AMFI-Registered Mutual Fund Distributor & SIF Distributor
ARN NO : 47791 (Date of initial registration – 17/02/2007; Current validity of ARN – 08/02/2027), PFRDA Reg. No. PoP 20092018, IRDAI Corporate Agent (Composite) : CA1099

This Certificate Demonstrates That IIFL As An Organization Has Defined And Put In Place Best-Practice Information Security Processes.


