3 Nov 2026 , 03:59 PM
Gold and silver enter Tuesday, November 3, amid heightened volatility following a sharp sell-off at the end of October. Spot gold recovered on Monday, November 2, closing near $3,948 an ounce, up approximately 1.9%, after touching its lowest level in 12 months on Friday. Spot silver also rebounded on Monday, closing near $50.63, up around 3.2%. However, the recovery proved short-lived, with early Tuesday trading seeing gold ease to around $3,919 and silver slip below the $50 mark to approximately $49.27. In India, MCX gold traded near ₹1,40,455 per 10 grams and MCX silver near ₹1,84,339 per kilogram during Monday’s evening session.
The longer story is still sobering. Spot gold is about 29% below this year’s high of $5,595, and silver is 58% below its intraday peak of $121.58, reached on January 29. Both metals are being repriced by a single question: how far, and how fast, will the Federal Reserve tighten? Earlier market estimates had placed the probability of a December rate hike at 83%. The latest futures-based estimate, cited by Kitco on November 2, is closer to 75%.
Friday October 30 was the sharpest day of a difficult month. Heavy liquidation across precious metals, and good returns, and technology-led equity sell-off triggered margin calls and forced selling of gold and silver to cover losses elsewhere. Gold settled at its lowest level in 12 months that day. The rebound on Monday came as crude oil fell sharply on signs of diplomacy with Iran, easing the inflation scare that had been driving rate expectations.
Over the month of October, spot gold fell about 6% and spot silver about 18.4%. Figure 1 shows the recent path, indexed to Friday’s close so that the two metals can be compared on one scale.
Gold pays no yield, so its appeal depends on what investors can earn elsewhere, and that return has been rising. The Fed raised its benchmark rate by a quarter point in September. On October 28 it held the target range at 3.75% to 4.00% on a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack dissenting in favour of a hike. The Fed is now led by Chair Kevin Warsh, who took the chair in May, and the central bank has kept the door open to further tightening.
Analysis: Metals have not been trading the October decision. They have been trading the December 8-9 meeting. Each hot data print raises the odds of a hike and weighs on bullion. That is why gold has fallen even as geopolitical risk has risen, the reverse of the usual pattern.
The growth and inflation data have been running hot. The US economy expanded at a 3.4% annualised pace in the third quarter, up from 2.2% in the second, according to Kitco’s summary of the official report. September headline PCE inflation rose 3.6% from a year earlier, and core PCE rose 3.1%. Monday’s ISM manufacturing index rose to 55.5, although its prices-paid gauge eased to 75.2 from 77.9. A partial offset came from Friday’s employment cost index, which showed third-quarter compensation growth slowing to 0.8% from 0.9%.
Yields remain high. The 10-year Treasury yield was trading near 4.9% on Monday, having eased as oil fell. The US dollar index was around 101.7 after extending recent losses, according to Trading Economics as reported by good returns. Although the weaker dollar provided some support to gold and silver on Monday, the broader interest-rate environment remains unfavourable for precious metals. Higher Treasury yields increase the opportunity cost of holding non-yielding assets such as gold and silver, while expectations of further monetary tightening can limit investment demand. Therefore, a temporary recovery in the dollar or a single session of lower yields may not be sufficient to reverse the broader downward trend.
Analysis: Gold and silver are increasingly responding to interest-rate expectations. Oil and the dollar function as transmission channels rather than the only direct causes of the decline. Gulf tensions can push crude prices higher, increasing inflation concerns and strengthening expectations of further rate hikes. Higher rate expectations can then lift bond yields, putting pressure on precious metals. Until this chain breaks, a single positive trading session may not be enough to signal a sustained recovery.
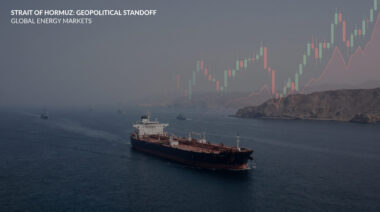
In a typical crisis, a war-risk headline lifts gold. In 2026 the relationship has run the other way, because the shock travels through energy and then through rates. Brent crude fell 7.6% on Monday to settle at $104.77 a barrel, and WTI settled at $96.46. The decline followed reports that Iranian and Qatari negotiators were circulating a draft proposal.
The diplomacy is real but unfinished. Iranian negotiators left Doha on Monday without a breakthrough, although messages continue through Qatari mediators. Iran’s proposal would have the United States end its blockade of Iranian ports and allow oil sales, while Iran reopens the Strait of Hormuz and nuclear talks follow. Washington has not accepted that sequence. Maritime risk is still visible: Qatar’s LNG tanker was struck by unidentified objects on Friday, and the UK Maritime Trade Operations centre reported a vessel hit by an unknown projectile on Sunday.
President Donald Trump said there would be no new strikes before the midterms but has not ruled out future military action. According to the Associated Press, Israeli Prime Minister Benjamin Netanyahu has urged Trump to consider another wave of strikes. That is why November 3 matters for oil and for gold alike.
Silver has been the sharper loser in both directions. It fell about 18.4% in October against 6% for gold, and it is down about 30% year to date, according to Forbes Advisor’s spot tracker. It also rebounded more strongly on Monday, rising about 3% against gold’s 2%.
Three factors explain the gap. First, silver has a monetary side and responds to real yields as gold does. Second, it has a large industrial side: solar, electronics and electric-vehicle manufacturers absorb a substantial share of demand, so a rate-driven slowdown in factories hits silver from two directions. Concerns about industrial demand and restrictive financing conditions still limit confidence in a sustained silver recovery. Third, silver ran much further in January. Its intraday high of $121.58 means it had more ground to give back, and the gold-to-silver ratio stood near 78 at Monday’s close from spot prices, a level that signals silver’s underperformance.
Analysis: Silver’s extra leverage to sentiment cuts both ways. MCX silver’s daily RSI was near 17 on Monday morning, signalling severely oversold conditions and often precedes sharp relief rallies. That is consistent with Monday’s bounce, but a technical signal of this kind does not establish a bottom.
Jewellery companies face two pressures. Higher duty-inclusive prices reduce volume, and sharp gold moves complicate inventory management. Kalyan Jewellers fell about 4%, and Titan dipped under 1% on the day the duty was raised. Kalyan’s first-quarter FY27 net profit rose 32% to ₹349 crore, but its shares fell about 7% on September 1 after Prime Minister Narendra Modi again urged citizens to restrain gold purchases. The World Gold Council estimated that the duty increase could reduce 2026 jewellery and investment demand by 50 to 60 tonnes.
Analysis: Lower prices can help jewellers by encouraging purchases, but the policy environment, with the duty and official appeals to limit buying, is the larger variable for volumes.
Gold-loan NBFCs such as Muthoot Finance and Manappuram Finance are exposed to collateral values. Under the RBI’s Lending Against Gold and Silver Collateral Directions, issued in June 2025 and effective from April 1, 2026, the maximum loan-to-value ratio is 85% for loans up to ₹2.5 lakh, 80% for loans between ₹2.5 lakh and ₹5 lakh, and 75% above ₹5 lakh. Bullet consumption loans are capped at 12 months (The Week, June 6, 2025).
Analysis: The arithmetic shows the squeeze. A loan equal to 80% of collateral value would breach the 85% cap if the gold’s value fell by about 6%. Above ₹5 lakh, the 75% cap leaves little or no headroom, so a borrower at the maximum could face a top-up request after any decline. The RBI’s Financial Stability Report warned that a prolonged fall in gold prices could raise defaults, and NBFC gold loans reached ₹3.41 lakh crore in June 2026, up 69.3% year on year, according to RBI data.
ETFs have continued to attract Indian investors, though not in a straight line. Gold ETFs took in ₹4,451 crore of net inflows in September 2026, up 71.4% from August, according to AMFI data, and silver ETFs took in ₹2,000 crore. Flows are not one-way: gold ETFs recorded a ₹725 crore outflow in May 2026, the first monthly outflow of the year at that point, per AMFI.
Analysis: Investors holding ETFs through a falling market should focus on their allocation and time horizon rather than daily prices. Adding in tranches is one way to avoid reacting to each move.
Technical levels, as of Monday, put first resistance for spot gold at $3,978 to $4,035, with a sustained break above that zone opening the way to $4,086. Support sits at $3,817, and a break below it targets $3,715. For silver, resistance is at $54.72 to $59.00, with support at $49.04 and then $45.66.
Bullish case (analysis): a cooler October jobs report on November 6, a soft CPI print and a Hormuz agreement would push oil and yields lower and reduce December hike odds. Gold could retrace toward the $4,000 to $4,100 zone that analysts identify as resistance. Silver would lead a rebound, as it did on Monday.
Bearish case (analysis): hot jobs and inflation data, a collapse of the Doha talks or renewed strikes after the midterms would lift oil and yields, raise December hike odds and test $3,817 and then $3,719 for gold, and $49 for silver.
The structural case is still contested. OCBC forecasts gold at $4,250 by the end of 2026 and $4,710 by the end of 2027, citing central-bank buying, ETF inflows and an eventual easing of Fed hawkishness. Those drivers are real, but they do not override the rate channel until it turns. For investors in India and globally, the most important number is the December hike probability, not the day’s MCX quote. What the Fed decides on December 9 will matter more for bullion than any single geopolitical headline
Related Tags


 IIFL Customer Care Number
(Gold/NCD/NBFC/Insurance/NPS)
1860-267-3000 / 7039-050-000
 IIFL Capital Services Support WhatsApp Number
+91 9892691696
Download The App Now


Follow us on


2026, IIFL Capital Services Ltd. All Rights Reserved

IIFL Capital Services Limited - Stock Broker SEBI Regn. No: INZ000164132 (Member ID - NSE: 10975 BSE: 179 MCX: 55995 NCDEX: 01249), DP SEBI Reg. No. IN-DP-185-2016, IA SEBI Regn. No: INA000000623, Merchant Banker SEBI Regn. No. INM000010940, RA SEBI Regn. No: INH000000248, BSE Enlistment Number (RA): 5016, AMFI-Registered Mutual Fund Distributor & SIF Distributor
ARN NO : 47791 (Date of initial registration – 17/02/2007; Current validity of ARN – 08/02/2027), PFRDA Reg. No. PoP 20092018, IRDAI Corporate Agent (Composite) : CA1099

This Certificate Demonstrates That IIFL As An Organization Has Defined And Put In Place Best-Practice Information Security Processes.